

Most owners of a single engine piston aircraft in the United States pay somewhere between $1,200 and $3,500 a year for full hull and liability cover. That is the honest headline, and it is also almost useless on its own, because the same aircraft can be quoted at both ends of that range depending on who is flying it.
What follows separates the parts that are written into law from the parts that are underwriting practice, because nearly every page on this subject blends the two, and it names where each number comes from so you can judge it yourself.

First, the part nobody tells you: it is not legally required
There is no federal requirement for a privately operated aircraft in the United States to carry insurance. Part 91, which covers private operations, sets out airworthiness, maintenance and pilot currency in detail and says nothing about insurance. You can legally own an aeroplane, fly it, and carry no policy at all.
Part 135 is different. A charter operator must carry liability cover to hold its certificate, which is the subject of our guide to private jet charter insurance requirements.
A handful of states do impose their own rule at registration. Minnesota is the clearest example. Under Minnesota Statutes section 360.59, subdivision 10, an owner registering an aircraft has to show liability cover of at least $100,000 per passenger seat, at least $100,000 for bodily injury or death to each person who is not a passenger, and at least $300,000 per occurrence for non passenger injury. The statute carves out exemptions, including certain aircraft on experimental certificates, collector aircraft built before 1939 and small unmanned aircraft, which instead have to show proof of insurability.
So the practical answer is that the law rarely forces your hand. Your lender does, your hangar landlord does, and the fixed base operator whose ramp you park on does. If the aircraft is financed, the bank will set the hull value and the deductible, and you will have no say in either.
What owners actually pay, by aircraft
Every published range below comes from aviation insurance brokers and training sites, which is worth knowing because brokers quote the numbers that bring enquiries. Treat them as the shape of the market rather than as a quote.
| Aircraft and pilot | Published annual range |
|---|---|
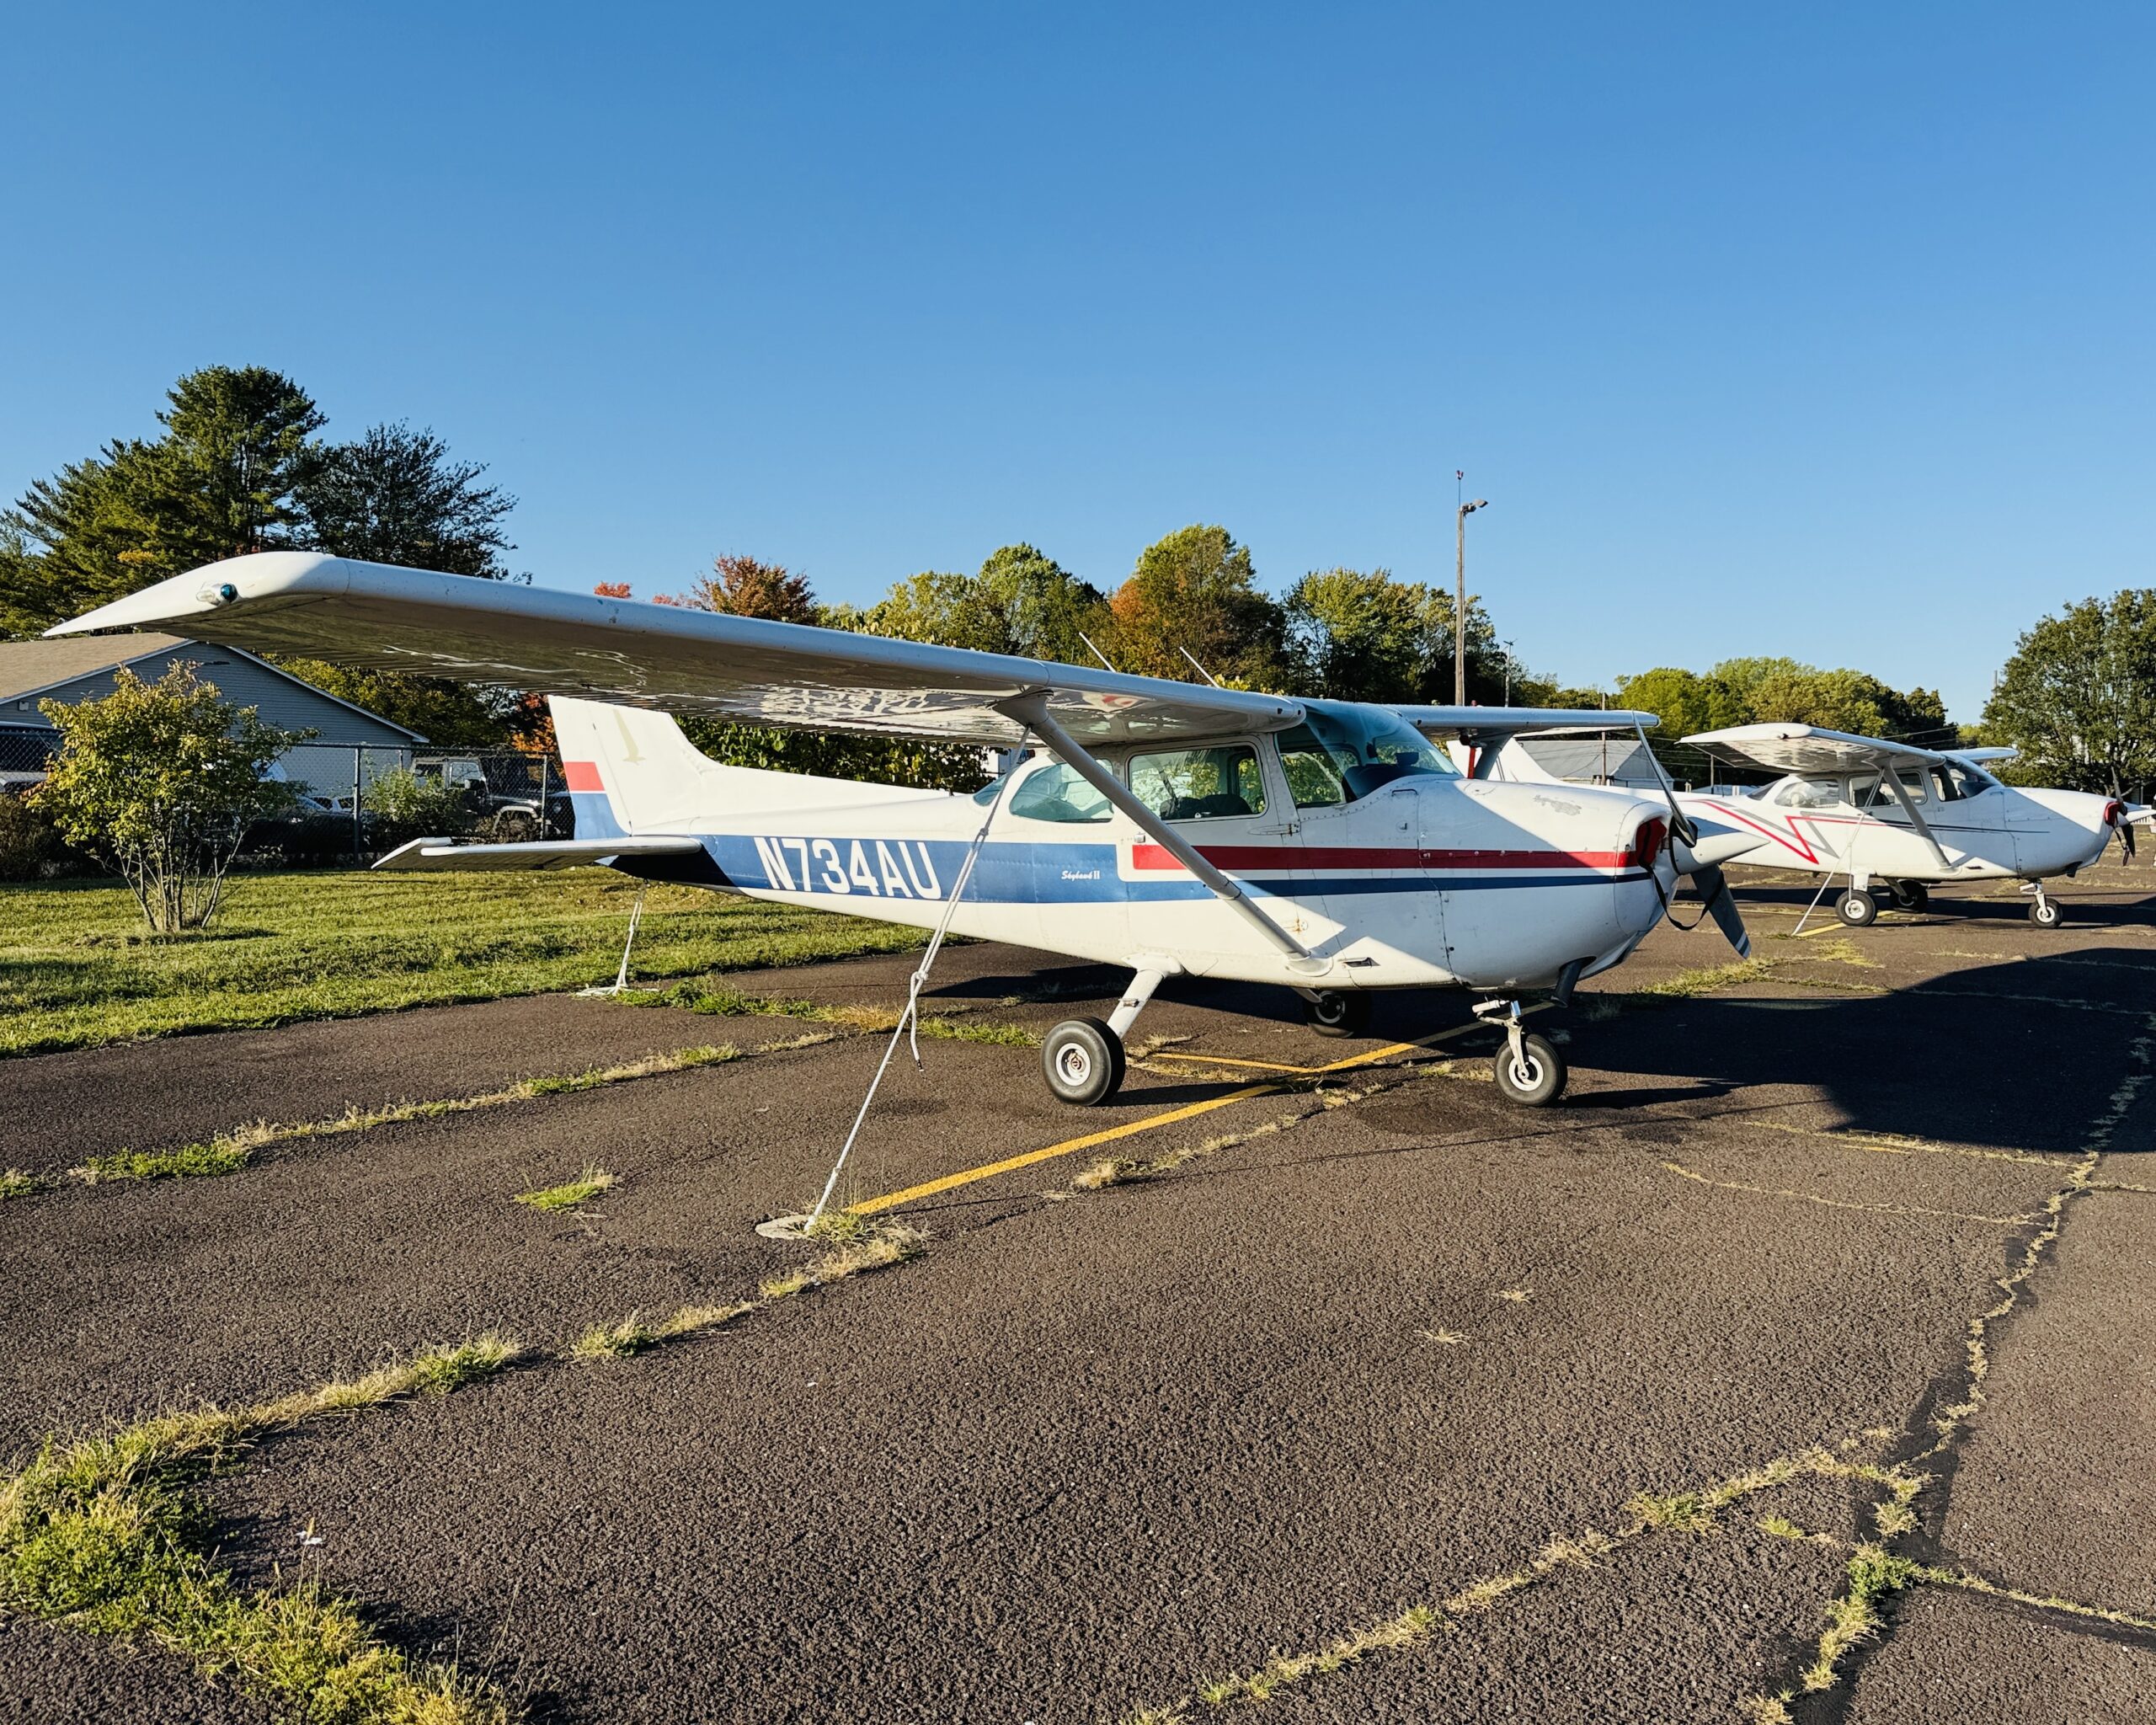
| Cessna 172, experienced owner pilot, full hull and liability | $1,200 to $2,500 |
| Cessna 172, low time pilot | $2,000 to $3,500 and up |
| Cessna 172 on a flight school or rental line | $4,000 to $8,000 and up |
| Cirrus SR22, mid range hull value | $3,000 to $6,000, with some guides quoting $5,500 to $10,000 |
| Cirrus SR22, low time pilot | $8,000 to $12,000, and some carriers decline without dual instruction |
| Liability only, experienced pilot | $150 to $300 |
| Non owned, or renter’s, cover | $100 to $500 |
Underneath all of it sits one rule of thumb that brokers return to repeatedly: hull cover on a piston single tends to land around 0.9 to 1.3 percent of the agreed hull value a year. On a $180,000 aircraft that is roughly $1,600 to $2,300 before liability, and it is the fastest sanity check on any quote you are handed.
Why the same aeroplane gets two very different quotes
Pilot experience moves the number more than anything else. Underwriters look at total time, time in type, whether you hold an instrument rating, and how recently you have flown. Time in type is the one owners underestimate, and it is one of the real costs of ownership that rarely appears in the budget alongside what the training itself cost. Two thousand hours in a 172 does very little for you on your first SR22 quote, and that is exactly where the open ended ranges above come from.
After the pilot, in rough order of how much they move a premium:
- Agreed hull value. You choose it, within reason, and the hull portion scales with it almost directly.
- Liability limits and sub limits. A smooth limit, meaning one figure that can be applied however a claim falls, costs more than the same headline number broken into a per passenger sub limit. Two policies can both say one million dollars and mean very different things.
- Retractable gear and higher performance. Gear up landings are frequent and expensive, and the rating reflects it.
- Where it lives. Hangared beats tied down outside, and hail and wind exposure are priced in regionally.
- Deductibles. Many piston policies carry no in motion deductible at all, which is unusual in insurance generally and is part of why these premiums are not lower.
- Claims history. A small claim can raise the renewal by more than the claim paid out, which is the arithmetic behind the standing advice to pay for minor damage yourself.
What the policy is actually made of
Two halves, and they are priced separately.
Liability covers what you do to other people and their property. It is the half that matters most and the half owners tend to buy least of.
Hull covers your own aircraft. It usually comes in two forms, and the distinction catches people out. Ground risk hull, sometimes called not in motion, covers the aircraft while it is parked, hangared or being moved by hand. All risk, or in motion, adds taxi, take off and flight. A policy quoted at a tempting number is sometimes ground risk only.
Then there are the pieces owners discover at claim time: whether passengers are covered at all, whether the policy follows the aircraft outside the United States, and whether anyone other than the named pilot may fly it. An open pilot warranty sets the minimum hours someone else must hold to be covered, and lending the aircraft to a friend who sits below that line effectively voids the cover for that flight.

The 2026 market: still soft, but the slope is flattening
This matters because it tells you whether to shop around. General aviation hull and liability rates have been falling since the hard market of the early 2020s, and through 2026 the broker market updates from Arthur J. Gallagher, Marsh and WTW all describe conditions as still soft, with plenty of underwriting capacity, while noting that the rate of decline has slowed.
Three things in that commentary are worth an owner’s attention. Clean claims histories are still being rewarded with real reductions. Second year reductions under long term agreements are getting harder to secure, which is an early sign of cooling. And hull war cover, the geopolitical piece, is the one segment being actively repriced upward.
The practical read is that this is a good year to remarket a policy you have held without shopping, and a poor year to assume the reduction you got last renewal repeats automatically.

Where owners overpay
Four patterns come up again and again.
Insuring to a number you invented. Hull value should track what the aircraft would actually sell for. Set it high and you pay for cover you will never collect, because the policy pays the agreed value, not more.
Claiming for small damage. A $200 claim that lifts a $2,000 premium to $2,400 costs you $200 in year one and keeps costing after that.
Buying training after the quote. Dual instruction, a type specific course and an instrument rating all move the premium, but only at renewal. Get the hours before the quote, not after it.
Staying with one broker out of habit. There are only a handful of aviation underwriters in the market, and a broker places with the ones they have relationships with. In a soft market that difference is real money.
If you are flying something larger
Everything above is about piston aircraft an owner flies personally. Turbine aircraft are underwritten on a different basis, with crew requirements, recurrent training in a simulator and liability limits an order of magnitude higher. We cover those numbers separately in our guide to private jet insurance.
Frequently asked questions
Is aircraft insurance required by law in the United States?
Not federally, for private Part 91 operations. Some states impose minimums at registration, Minnesota being the clearest, and lenders, hangar landlords and fixed base operators impose their own requirements regardless.
How much is insurance on a Cessna 172?
Published ranges put an experienced owner pilot at roughly $1,200 to $2,500 a year for full hull and liability, a low time pilot higher, and a flight school line considerably higher again.
Does insurance cost more than the aircraft is worth over time?
At around 1 percent of hull value a year, a policy held for a decade costs roughly a tenth of the aircraft. That is usually less than one year of hangarage plus maintenance, and far less than a single liability claim.
Can I insure an aircraft I do not own?
Yes. Non owned, or renter’s, cover protects you when you fly a club or rental aircraft, and published ranges put it at $100 to $500 a year. The owner’s policy protects the owner, not you.
Will a claim raise my premium?
Almost always, and often by more over the following years than the claim paid out. That is why experienced owners carry a deductible they can afford to absorb and treat small damage as a cost of ownership.
What is an open pilot warranty?
The clause that sets the minimum qualifications anyone other than the named pilot must hold to be covered. If the person flying sits below it, the cover does not respond.